Your hail deductible, in dollars.
Many Texas home policies set the wind and hail deductible as a percentage of what the house is insured for. Move the numbers and see what a roof claim would cost you.
You pay
$7,600
- You pay
- $7,600
- The policy pays
- $10,900
On an $18,500 roof, a 2% deductible leaves you with $7,600 and the policy with $10,900.
An illustration with round numbers. It is not a quote, and your policy may work differently. The percentage is applied to your dwelling coverage, the amount the house is insured for. Have us read your policy.
How big was the hail?
The National Weather Service office in Fort Worth sizes hail against things you already own. A storm counts as severe once the stones reach one inch across, the size of a quarter.
- Pea0.25 in
- Penny0.75 in
- Quarter1 in
- Golf ball1.75 in
- Baseball2.75 in
Drawn to scale against each other. Sizes from the National Weather Service office in Fort Worth.
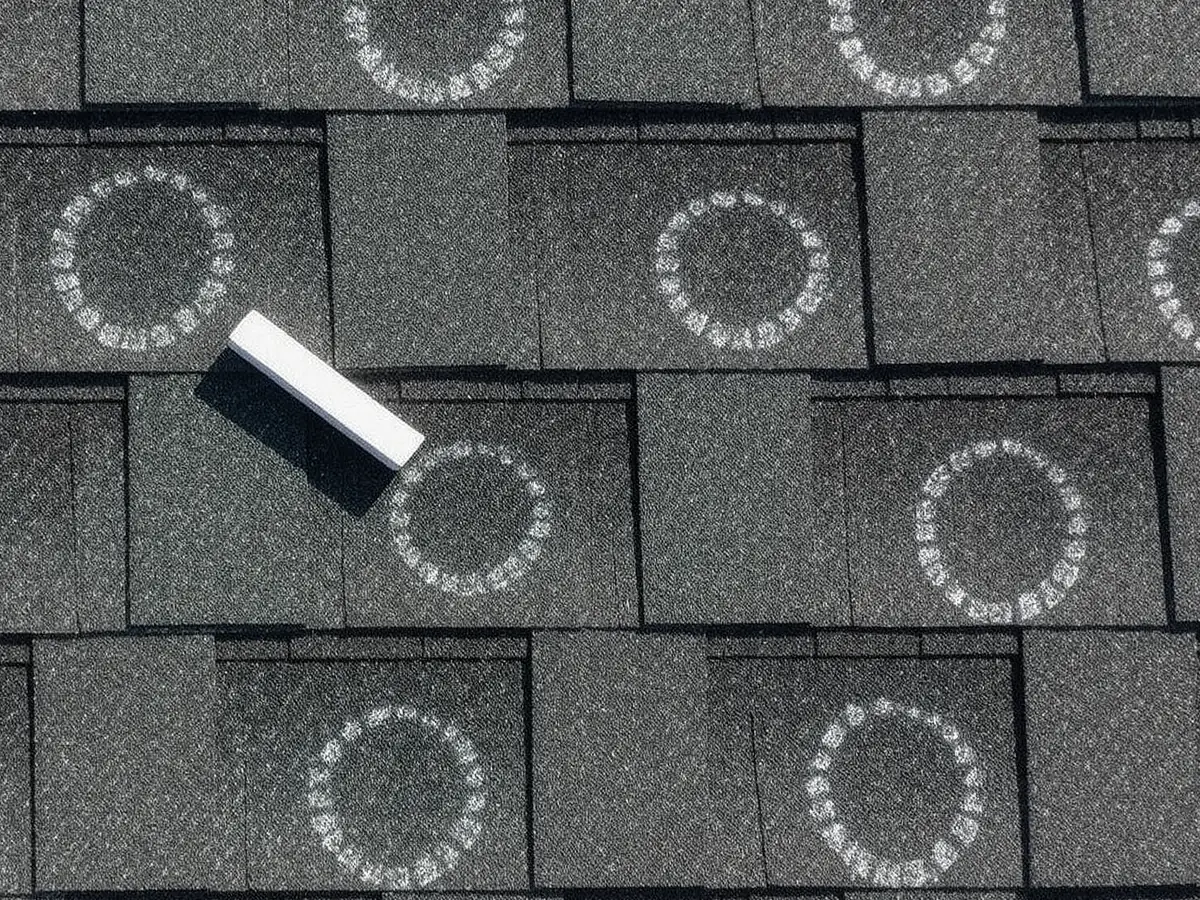
After a storm, in this order
- Take photos of the roof, the gutters and the car before anything is cleaned up.
- Call us before a roofer asks you to sign anything.
- We compare the repair estimate with your deductible, so you know whether a claim pays before you file one.
What does 30/60/25 mean?
It is the least auto liability coverage Texas lets you drive with. Each number is in thousands of dollars.
- 30
$30,000 for each injured person
What your policy pays toward one person's injuries when a wreck is your fault.
- 60
$60,000 for each accident
The most it pays for everyone's injuries in one wreck, however many people are hurt.
- 25
$25,000 for property damage
What it pays to fix the other driver's vehicle. Many new trucks cost more than this.
Every Texas auto policy also includes personal injury protection unless you turned it down in writing, and your insurer has to offer uninsured motorist coverage. Read the auto page.
What does Sideoats write?
We are an independent agency, so your policy can be placed with the carrier that fits and checked against the others at renewal.
Home
Hail, wind, fire and theft, with the deductible worked out in dollars before you sign.
Auto
The Texas minimum is 30/60/25. We show you what the next step up covers.
Renters
Your landlord's policy covers the building. This one covers what is inside it.
Flood
Home policies do not cover flooding, and most flood policies take 30 days to start.
Business
General liability, commercial auto and property for shops, trades and offices.
Umbrella
Extra liability coverage that sits on top of your home and auto policies.
Who reads your policy?
Rosalind Ibarra
Principal agent
Rosalind opened Sideoats in 2011 after twelve years as a claims adjuster. She has stood on a lot of Fort Worth roofs, and she reads every renewal before it goes out.
Desmond Achterberg
Commercial lines
Desmond writes coverage for contractors, restaurants and small shops. He asks how your truck is used before he quotes it.
Tova Pruitt
Personal lines
Tova handles home and auto, and she is the person most likely to pick up the phone.
Fictional people, written for this demo. About the agency.
What do clients say?
Rosalind put my deductible in dollars on one page. I had paid for that policy for six years and never knew the number.
After the April storm they told me the repair was under my deductible before I filed anything. I was glad to know that first.
Desmond asked how each of my trucks was used and found two that were on the wrong policy.
Where is the office?
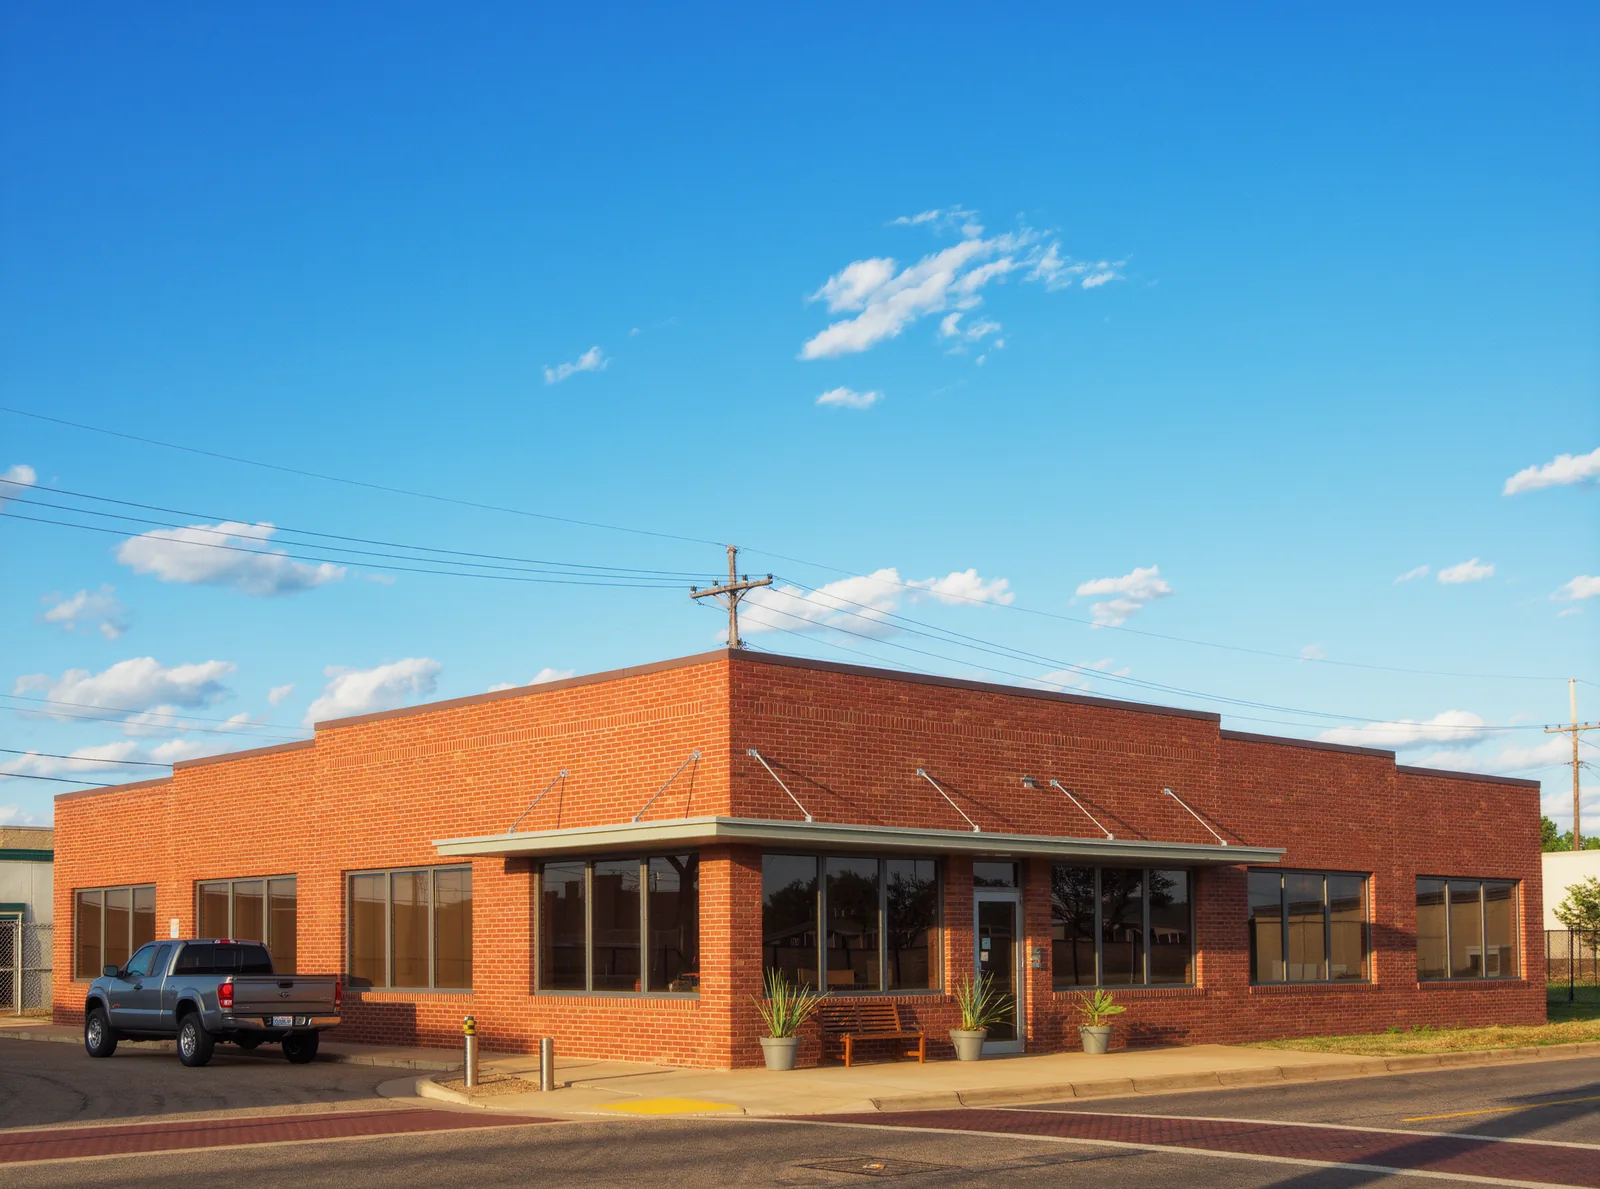
We are on Magnolia Avenue in the Near Southside of Fort Worth, in a brick building with parking at the curb. Walk in with your policy and we will read it with you, or ask and we will come to your kitchen table.
We write policies across Tarrant County, and most of our clients live within a short drive of the office.
| Monday to Friday | 8:30 AM to 5:30 PM |
|---|---|
| Saturday and Sunday | By appointment |
Where do you write policies?
All of Tarrant County. The office is on Magnolia Avenue in the Near Southside, and each of these places has a page on what we see there.
Questions we answer every week
What is a percentage deductible?
It is a deductible set as a share of what your house is insured for. On a house insured for $380,000, a 2% wind and hail deductible is $7,600. You pay that amount on each claim before the policy pays anything. The hail deductible guide has a table for other house values.
Does home insurance cover hail damage in Fort Worth?
Most home policies cover windstorm and hail. The deductible comes out first, and for wind and hail it is often a percentage of what the house is insured for. The example at the top of this page shows that deductible in dollars.
Does home insurance cover flooding in Texas?
No. Home policies do not cover flooding. Flood insurance is a separate policy, and most flood policies have a 30 day waiting period before they start, so it has to be in place before a storm is on the forecast.
What is the minimum auto insurance in Texas?
Texas requires liability coverage of at least $30,000 for each injured person, up to $60,000 per accident, and $25,000 for property damage. It is written as 30/60/25. The auto page explains where those numbers run out.
What is an independent insurance agency?
An independent agency is not tied to one insurance company. We place your policy with the carrier that fits, and at renewal we can check it against the others we represent.
How do I check that an agent is licensed in Texas?
Call the Texas Department of Insurance help line at 800-252-3439, or use the agent lookup on the department's website. Every Texas agent and agency has a license number you can ask for.
Have us read your policy
Send four details and an agent calls back the same business day. Bring your current policy to the call and we will find the deductible together.
Monday to Friday, 8:30 AM to 5:30 PM Central. Magnolia Avenue, Near Southside, Fort Worth.