Insurance for Fairmount homes
Fairmount is next door to our office, and most of its houses are older than any policy form in use today.
When Fairmount's building boom began
1905
The largest concentration of houses in the district dates from 1905 to 1920. Rebuilding one costs more than its age suggests.
What should a Fairmount homeowner know?
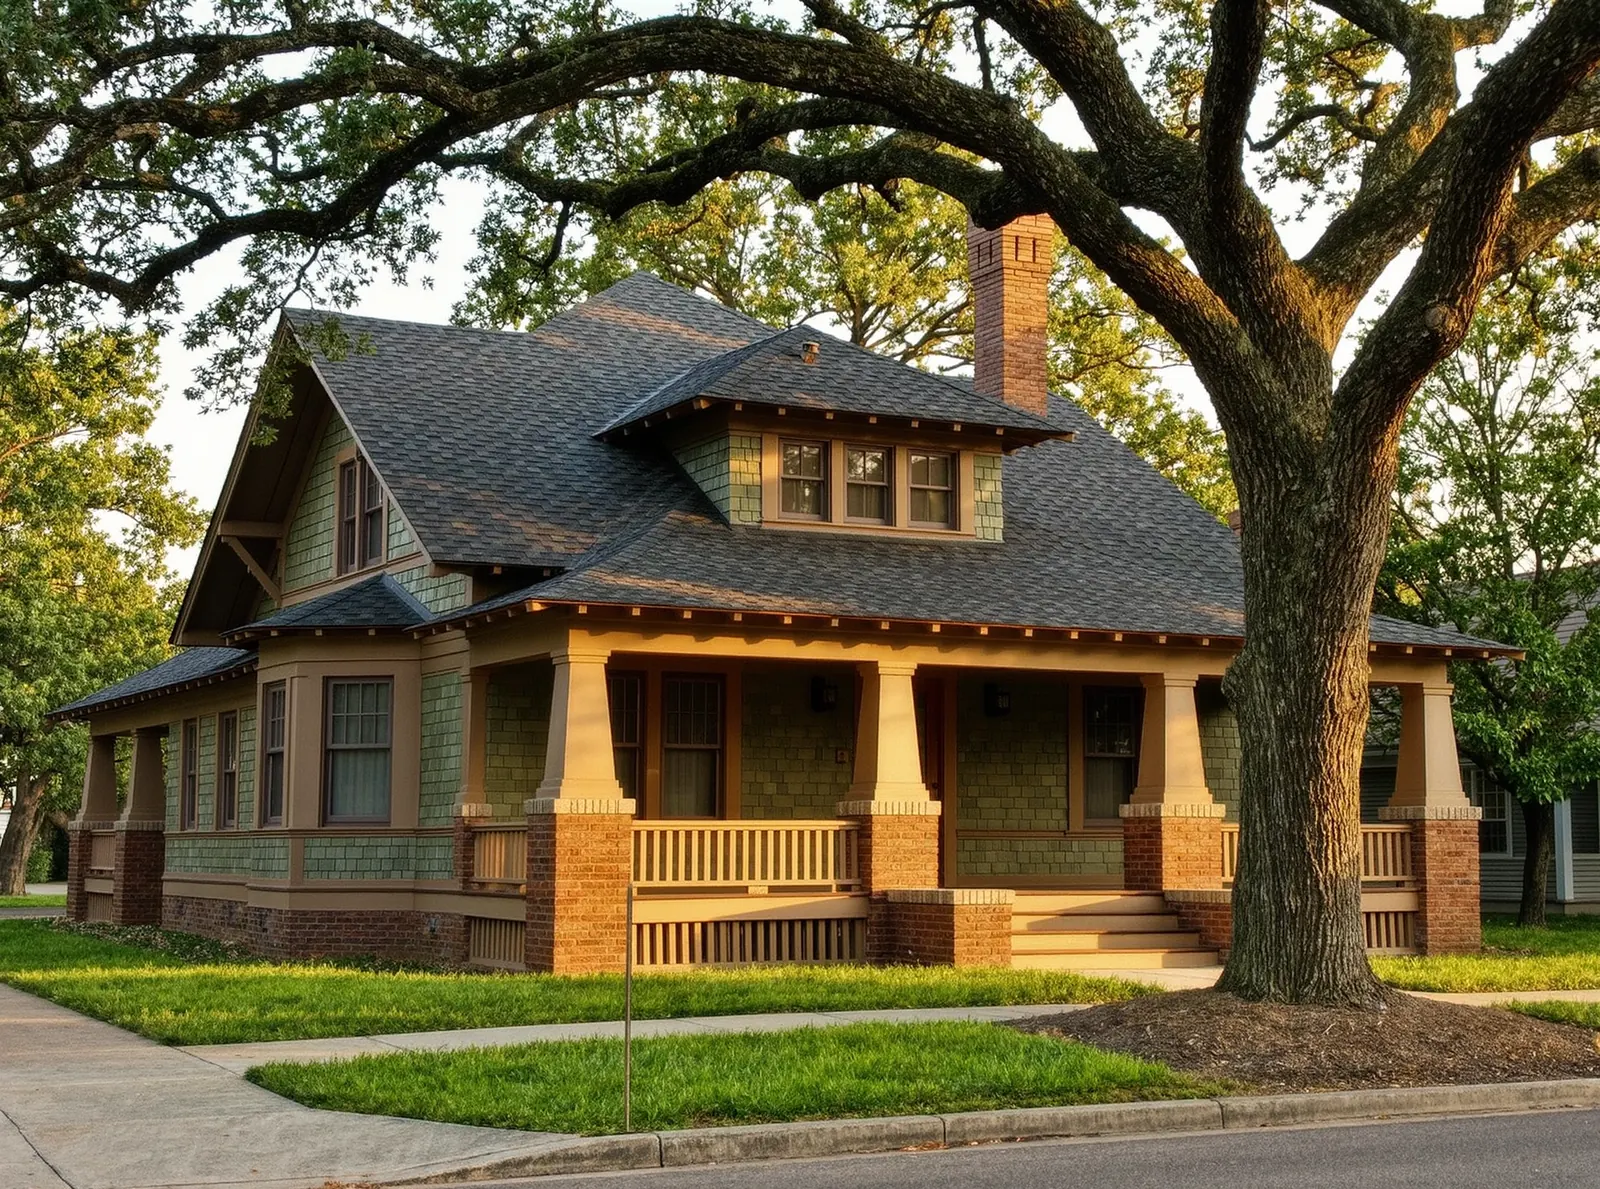
Fairmount was developed as a middle class neighborhood between 1890 and 1938 and covers about 375 acres. Wood frame bungalows are the most common house, with Four Squares scattered through the district, and it is listed on the National Register of Historic Places.
For insurance, age changes two things. Rebuilding a 1915 bungalow with matching materials and trim costs more than rebuilding a newer house of the same size, so the dwelling limit needs a careful look. Carriers also ask about the wiring, the plumbing and the roof before they quote.
The city publishes design guidelines for the district that cover roofing, windows and siding. Check them before a roof claim turns into a roof replacement.
What do we plan for here?
| What we see here | What we do about it |
|---|---|
| Original siding, trim and porches | We check that the dwelling limit matches the cost to rebuild, which is separate from the sale price |
| Wiring and plumbing of mixed ages | Carriers ask. We find the ones that write older homes and tell you what they will want to see |
| Roofs in a historic district | We read the roof section with you: replacement cost or actual cash value, and the hail deductible in dollars |
What do you write in Fairmount?
We are an independent agency, so your policy can be placed with the carrier that fits and checked against the others at renewal.
Home
Hail, wind, fire and theft, with the deductible worked out in dollars before you sign.
Auto
The Texas minimum is 30/60/25. We show you what the next step up covers.
Renters
Your landlord's policy covers the building. This one covers what is inside it.
Flood
Home policies do not cover flooding, and most flood policies take 30 days to start.
Business
General liability, commercial auto and property for shops, trades and offices.
Umbrella
Extra liability coverage that sits on top of your home and auto policies.
Where else do you write policies?
All of Tarrant County. The office is on Magnolia Avenue in the Near Southside, and each of these places has a page on what we see there.
Fairmount insurance, answered
Does an older house cost more to insure?
Often, because it costs more to rebuild and carriers look closely at wiring, plumbing and roofs. Updates you can document help.
What is replacement cost on a historic home?
It is what it would cost to rebuild the house at current prices. On a house with original trim and materials, that is usually higher than a standard estimate assumes.
Do I need approval to replace my roof in Fairmount?
The district has design guidelines that cover roofing. Ask the city's historic preservation office before work starts.
Have us read your policy
Send four details and an agent calls back the same business day. Bring your current policy to the call and we will find the deductible together.
Monday to Friday, 8:30 AM to 5:30 PM Central. Magnolia Avenue, Near Southside, Fort Worth.